Plus, NFIP vs. state-backed flood insurance
 The Trump administration is fighting an ongoing effort by ten Republican-led states to ditch FEMA’s Risk Rating 2.0 flood insurance pricing, a new report throws water on the idea of shrinking the National Flood Insurance Program into separate state-run systems, and FEMA releases a best practices guide for retrofitting flood-prone homes. It’s all in this week’s Flood Digest.
 The Fight Against Risk Rating 2.0: 2023 marked the beginning of a lengthy process: Louisiana led a band of 10 Republican states, including Florida, that filed suit against the federal government for “unfair” flood insurance rate increases under FEMA’s Risk Rating 2.0 program. Now, in a rare turn of events, the Trump administration is voicing support for the Biden-era program, asking a federal judge to dismiss the states’ lawsuit in a 126-page court filing. The administration contends the old program was too costly, following years of artificially low flood premiums, and have cited findings from the recent FEMA Review Council report to back up its arguments. It is worth noting that four of the key council members hail from states that filed the lawsuit: former Mississippi Gov. Phil Bryant (R); former Florida emergency management chief Kevin Guthrie; Texas Gov. Greg Abbott (R); and Texas emergency management chief Nim Kidd.
“This may be one of the first concrete actions we’re seeing as an outcome of the (council) report,” said Chad Berginnis, executive director of the Association of State Floodplain Managers, which supports Risk Rating 2.0’s rates, in an interview with E&E News.
An earlier 2024 Biden-era motion to dismiss the case was denied and both sides are scheduled to submit briefs this November, but in the meantime, the involved states have been anything but quiet. Congressman Troy A. Carter, Sr. (D-LA) recently sent a letter to DHS Secretary Markwayne Mullin and FEMA Administrator Cameron Hamilton, among other important emergency management figures, rallying against the privatization suggestions in the FEMA Review Council report. Rep. Carter, who leads the bipartisan Flood Resilience Caucus, offered seven policy suggestions, including the empowerment of local communities, updating Risk Rating 2.0, and two things we have long advocated for here at LMA: revising the ‘Write Your Own’ agent compensation, and a depopulation of existing NFIP policies into the private market.
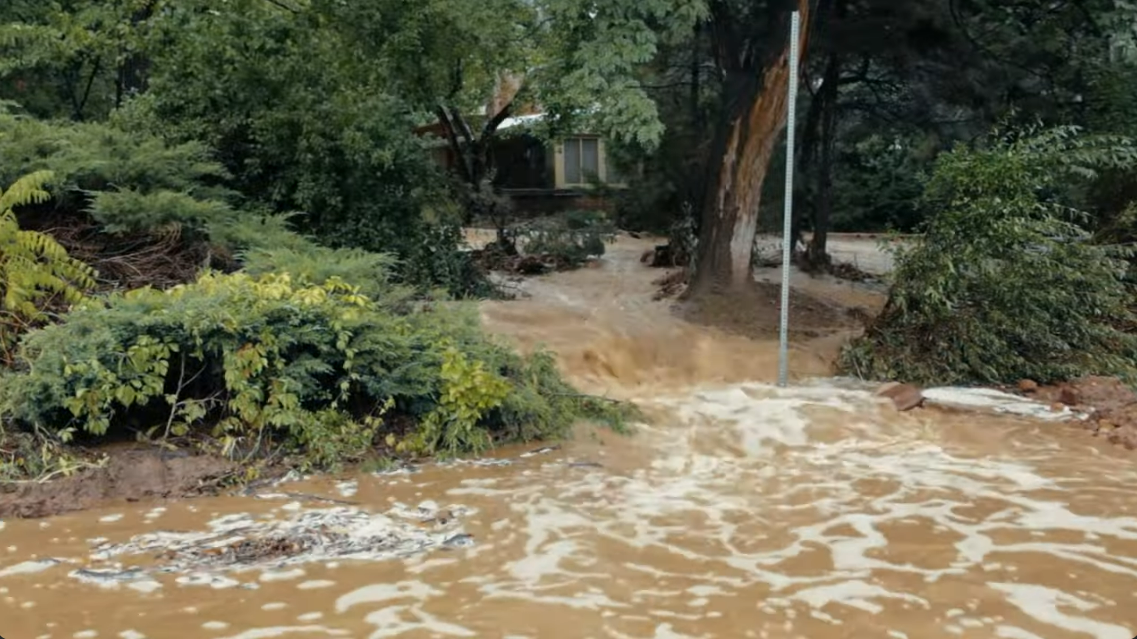
Flash flooding of neighborhood homes. Courtesy, FEMA
Floods without Borders: Part of the debate from the FEMA Review Council report is whether states should take on more responsibility for flood insurance instead of relying on the federal government. But new research from Arizona State University and Columbia University suggests that shrinking the National Flood Insurance Program (NFIP) into separate, state-run systems could actually make it harder to recover from major disasters. Their report says this line of thinking may not only be misinformed, but incredibly detrimental to the risk pooling of the NFIP, which has historically increased financial resilience nationwide. The idea isn’t new in the insurance landscape: a broader risk pool with different places facing different hazards means premiums generally stay lower as the overall odds of catastrophic risk are lower. Another key takeaway: the interconnectedness of disasters irrespective of our manmade borders, via a phenomenon called “hyperclusters” coined by the researchers. They provide the example of a hurricane causing flooding along the Gulf Coast, before causing heavy rainfall further inland. While traditional thought might consider these separate events, they are both linked to the same atmospheric drivers, or, one hypercluster. This perspective allows for a more nuanced and realistic picture of cascading loss and failures, and how resilience and disaster preparedness may extend far outside of any one local community.

A flood berm protecting a residence. Courtesy, FEMA
FEMA Retrofitting Guidelines: FEMA recently updated its Engineering Principles and Practices for Retrofitting Flood-Prone Residential Structures (FEMA P-259), a best practices guide to help reduce cyclical flood damage in flood-prone areas. Essentially, buildings that predate the adoption of local floodplain management requirements are much more likely to sustain higher flood damage over time. Retrofitting efforts, such as home elevation, relocation, barriers, dry floodproofing, and wet floodproofing can all reduce the likelihood of flood damage significantly, lowering the overall risk pool for the NFIP, and saving countless lives and dollars in the process.
 LMA Newsletter of 8-31-26